

Contents
Personal income tax (PIT) on a Vietnamese salary in 2026 is worked out by taking taxable income, subtracting compulsory insurance and the family deductions, and applying a five-bracket progressive scale of 5%, 10%, 20%, 30% and 35%. The new deductions are VND 15.5 million a month for yourself and VND 6.2 million for each registered dependant. A gross salary of VND 30m with no dependants, for example, pays VND 635,000 tax a month.
Key takeaways
- The five-bracket scale comes from the Personal Income Tax Law No. 109/2025/QH15 and applies to employment income from the 2026 tax year.
- Family deductions under Resolution 110/2025/UBTVQH15: VND 15.5m a month for the taxpayer, VND 6.2m a month per dependant.
- Taxable income = assessable income − compulsory insurance − family deductions.
- The first bracket is wider than before: the first VND 10m of taxable income is taxed at 5%.
- If taxable income is zero or negative, no tax is due.
The 2026 tax brackets
| Bracket | Monthly taxable income | Rate | Shortcut formula |
|---|---|---|---|
| 1 | Up to VND 10m | 5% | 5% × TI |
| 2 | Over VND 10m to 30m | 10% | 10% × TI − 0.5m |
| 3 | Over VND 30m to 60m | 20% | 20% × TI − 3.5m |
| 4 | Over VND 60m to 100m | 30% | 30% × TI − 9.5m |
| 5 | Over VND 100m | 35% | 35% × TI − 14.5m |
TI: taxable income. The shortcut column gives the same result as adding up each bracket separately.
The previous table, used up to the 2025 tax year, had seven brackets and the first one stopped at VND 5m. With a wider low bracket and higher deductions, most employees pay noticeably less tax in 2026.
The formula
1. Assessable income
This is your salary, wages, bonuses and allowances for the month, minus the items the law exempts (certain allowances, mid-shift meals within the legal limit and so on). For most employees without special allowances it equals the gross salary.
2. What you can deduct
- Compulsory insurance paid by the employee: social insurance 8%, health insurance 1.5% and unemployment insurance 1% of the insured salary, each with a cap.
- Personal deduction: VND 15,500,000 a month.
- Dependant deduction: VND 6,200,000 per person per month, only once the dependant is registered with the tax authority through your employer or by yourself.
- Qualifying charitable contributions and voluntary pension fund contributions, where they meet the rules.
3. Taxable income and tax due
Taxable income = assessable income − deductions. Apply the table above to whatever is left.
Worked examples
All three assume the insured salary equals the gross salary, work in region I and the rules in force from 1 July 2026. You can check each one in the personal income tax calculator.
Example 1: VND 30m, no dependants
- Insurance: 30,000,000 × 10.5% = VND 3,150,000.
- Taxable income: 30,000,000 − 3,150,000 − 15,500,000 = VND 11,350,000.
- Tax: 10,000,000 × 5% + 1,350,000 × 10% = 500,000 + 135,000 = VND 635,000.
- Shortcut check: 10% × 11,350,000 − 500,000 = VND 635,000.
Example 2: VND 50m, one dependant
- Insurance: 50,000,000 × 10.5% = VND 5,250,000.
- Taxable income: 50,000,000 − 5,250,000 − 15,500,000 − 6,200,000 = VND 23,050,000.
- Tax: 10% × 23,050,000 − 500,000 = VND 1,805,000.
Example 3: VND 100m, no dependants
At this level the insurance caps apply. From 1 July 2026 the base salary is VND 2,530,000, so the cap for social and health insurance is VND 50,600,000; the unemployment insurance cap in region I is VND 106,200,000.
- Social insurance: 50,600,000 × 8% = VND 4,048,000.
- Health insurance: 50,600,000 × 1.5% = VND 759,000.
- Unemployment insurance: 100,000,000 × 1% = VND 1,000,000.
- Total insurance: VND 5,807,000.
- Taxable income: 100,000,000 − 5,807,000 − 15,500,000 = VND 78,693,000.
- Tax: 30% × 78,693,000 − 9,500,000 = VND 14,107,900.
Monthly tax by salary
| Gross salary | 0 dependants | 1 dependant | 2 dependants |
|---|---|---|---|
| VND 20,000,000 | VND 120,000 | VND 0 | VND 0 |
| VND 25,000,000 | VND 343,750 | VND 33,750 | VND 0 |
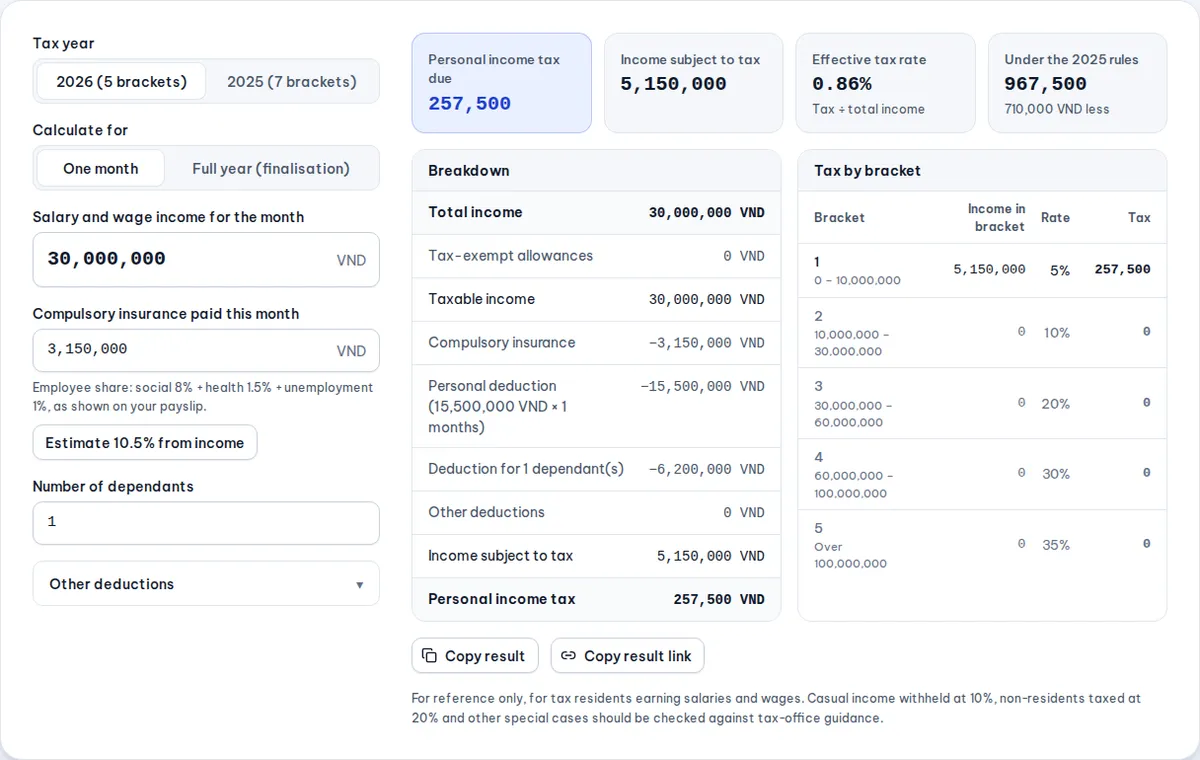
| VND 30,000,000 | VND 635,000 | VND 257,500 | VND 0 |
| VND 40,000,000 | VND 1,530,000 | VND 910,000 | VND 395,000 |
| VND 50,000,000 | VND 2,425,000 | VND 1,805,000 | VND 1,185,000 |
Monthly tax, region I, insured salary equal to gross salary, from 1 July 2026.
Who counts as a dependant?
The most common dependants are:
- children under 18; adult children with a disability who cannot work; children in university, college or vocational training with no income or only a low income;
- a spouse, parents or parents-in-law past working age or unable to work, with no income or only a low income.
Each dependant can be claimed by one taxpayer only, so working couples need to agree who registers the children.
Residents and non-residents
The table and deductions above are for tax residents, which in practice covers most people who live in Vietnam for 183 days or more in a tax year or have a registered permanent residence here. Non-resident individuals are taxed differently on their Vietnam-sourced employment income (a flat rate on gross income, without the family deductions). If you are not sure which group you fall into, check with your employer's payroll team before relying on the calculator.
Common mistakes
- Forgetting to subtract insurance before the family deductions. Insurance is deductible; skipping it overstates your tax.
- Applying the top rate to all income. The scale is progressive: only the part above each threshold is taxed at the higher rate.
- Using the old deductions. From the 2026 tax year, VND 11m and VND 4.4m no longer apply.
- Registering a dependant without a tax code for that person. Incomplete dependant files can be rejected at year-end finalisation.
To see the tax alongside your take-home pay, use the gross-to-net salary calculator or read the worked example what a VND 20m salary really pays.
Frequently asked questions
At what salary do you start paying PIT in 2026?
With salary income only, no dependants and insurance on the full salary, tax starts once gross pay passes about VND 17.3m a month (17.32m minus 10.5% insurance is roughly 15.5m). Each dependant raises that threshold by about VND 6.9m.
When does the five-bracket table start?
It applies to employment income from the 2026 tax year. At the 2026 year-end finalisation, the whole year's income is assessed with the new table and the new deductions.
Is the Tết bonus taxed?
Yes. A cash bonus is assessable income and is added to the income of the month you receive it. Because the scale is progressive, more tax is usually withheld that month; the difference is settled when the year is finalised.
What if my insurance is paid on a basic salary only?
Less insurance is deducted, so taxable income and tax are slightly higher. Because you also contribute less, your take-home pay is usually still higher overall.
Can the calculator replace the annual tax return?
No. It estimates the monthly tax with the brackets and deductions currently in force. At finalisation you still file the official forms based on your actual income for the year.
Free tools used in this article
#vietnam income tax#PIT brackets#dependant deduction#2026